
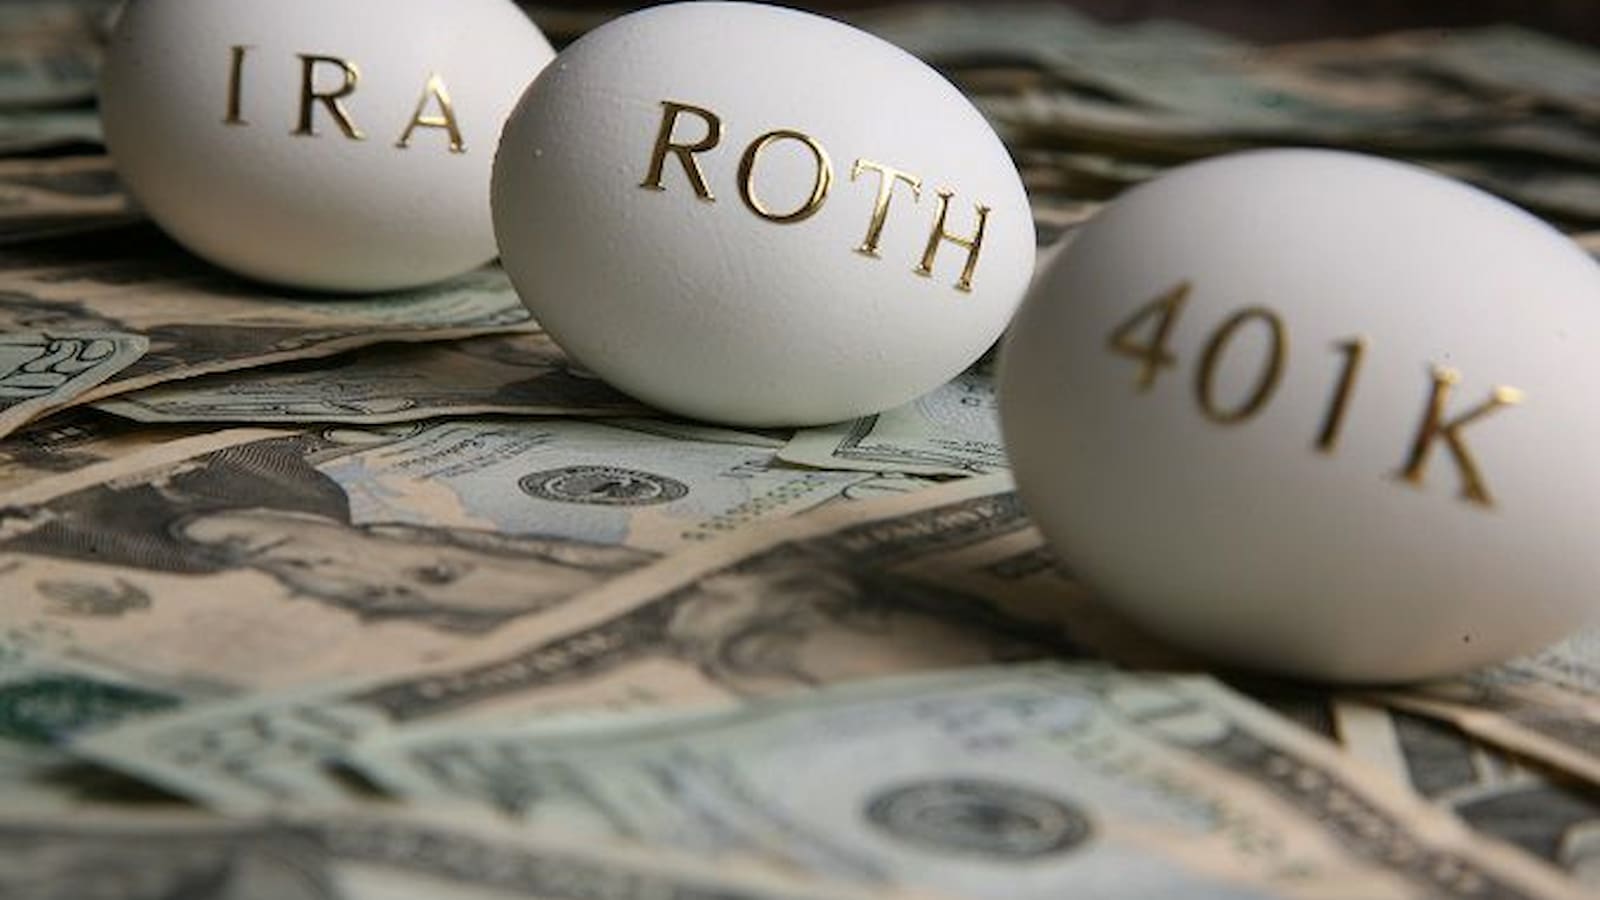
Lower Taxes on Retirement Savings: A couple retiring at age 64 with $1.2 million in a fully pretax 401(k) may feel that they have saved enough money for retirement. They also have enough money in a taxable investment account to pay their bills for several years. Because of this, they plan to leave their 401(k) untouched and allow the money to grow.
But there is something they need to think about. The money in their 401(k) has not been taxed yet. They will generally have to pay income tax when they withdraw it. The longer they leave the money in the account, the larger the balance could become, which may also lead to larger taxable withdrawals in the future.
The years between retirement and the start of required minimum distributions (RMDs) can give them a chance to manage their taxes. If they plan carefully, they may be able to pay tax on some of their retirement savings at lower rates instead of waiting until they have to take larger withdrawals later.
How Much Money Do You Need to Retire at 65? Check the Savings You May Need
Map Every Income Source Before Touching the Account
The first thing the couple should do is make a year by year retirement income plan. They need to know when their regular salary will stop, when their pension payments will begin, when they plan to claim Social Security and when they will need to start taking money from their retirement accounts. This will help them understand how much income they may have in each year and how much tax they could have to pay.
For example if both spouses stop working at age 64 but delay Social Security, their taxable income may fall for a few years. They could use this period to move some money from their pretax retirement savings into a Roth IRA.
Under current law, people who reach age 74 after December 31, 2032, generally have to start RMDs at age 75. A couple who are both 64 in 2026 would generally fall under this rule. The age requirement comes from the SECURE 2.0 Act. It’s important to check the rules that apply to each person’s account before making a decision.
These years between retirement and RMDs can be useful because the couple may have less taxable income than they did while working. They may be able to convert some of their 401(k) savings into a Roth IRA while staying within a lower tax bracket.
A Roth conversion means moving pretax retirement money into a Roth account. The amount converted is generally added to taxable income for that year. Once the money is in the Roth IRA, qualified withdrawals can be tax-free, and the original account owner does not have to take RMDs from a Roth IRA during their lifetime.
How Much Could Their First Required Withdrawal Be?
Required minimum distributions are the amounts that retirees must withdraw from certain retirement accounts once they reach the applicable age. The amount is generally worked out using the account balance at the end of the previous year and an IRS life expectancy factor. Suppose the couple is 75 and their combined pretax retirement savings still total $1.2 million. Using the usual IRS Uniform Lifetime Table, the distribution factor at age 75 is 24.6.
| Details | Amount |
|---|---|
| Combined 401(k) savings | $1,200,000 |
| IRS distribution factor at age 75 | 24.6 |
| Approximate required withdrawal | $48,780 |
This means the couple may need to withdraw about $48,780 in that year if their combined balance is still $1.2 million and both use the same distribution factor. The IRS calculation must still be done separately for each person’s account. The amount will change based on their actual account balances and ages.
10 Cheapest States for Retirement in 2026: Check Housing and Living Costs
The entire withdrawal is not necessarily the amount they will owe in tax. The tax bill depends on their total income, deductions and other details of their tax return. But the withdrawal can add to their taxable income even if they do not need all the money to pay their living costs.
They should also know that the first RMD may be delayed until April 1 of the year after the year they reach the required beginning age. But if they use this extra time, they may have to take two RMDs in that following year the first year’s withdrawal and the second year’s withdrawal.
RMD amount can increase if their investments grow. On the other hand, spending from the account or making Roth conversions earlier may reduce the balance left for future withdrawals. Failing to take the full required amount can also lead to an excise tax of 25% of the shortfall. This can be reduced to 10% if the missed amount is corrected within the required correction window and the other conditions are met.
Compare Two Retirement Plans Side by Side
| Plan A: Leave the 401(k) Alone | Plan B: Make Roth Conversions |
|---|---|
| Use cash and other income to pay living costs. | Convert some pretax savings into a Roth IRA each year. |
| Allow the 401(k) balance to keep growing. | Pay tax on converted amounts in the year of conversion. |
| RMDs may be larger in later years if the account grows. | Future RMDs may be lower because some money has moved out of the pretax account. |
| More income in later years could make more Social Security benefits taxable. | Smaller future RMDs may help manage taxable income later. |
| Medicare premiums could rise if income crosses the required limits. | Conversions could also raise income enough to increase Medicare premiums. |
How 401(k) Withdrawals Can Affect Social Security and Medicare
Social Security benefits may become taxable
The amount of Social Security that is taxable depends on the couple’s total income. The calculation includes half of their Social Security benefits along with other income, including taxable retirement withdrawals and tax-exempt interest.
Social Security Claiming Age Clarity Act: Retirement Age Is Not Going Up
Depending on their income, up to 85% of their Social Security benefits may be included in taxable income. This does not mean they pay an 85% tax rate on their benefits. It means that up to 85% of the benefit amount may be taxable. If the couple starts taking large RMDs on top of Social Security, they could end up paying tax on more of their benefits.
Medicare premiums could also increase
Medicare premiums can also be affected by income. For certain beneficiaries, the Social Security Administration uses income reported on a tax return from two years earlier to work out whether higher Medicare Part B and Part D premiums apply. These extra charges are known as income-related monthly adjustment amounts, or IRMAA.
This means a large 401(k) withdrawal or Roth conversion could affect Medicare costs in a later year. The couple needs to consider this before deciding how much money to convert.
They should also plan for the possibility that one spouse may die before the other. After a spouse’s death, the surviving partner may have to file as a single taxpayer and face different tax brackets. The surviving spouse could have a similar amount of income but pay more tax than they did when filing jointly.
 may feel that they have saved)